FIX & FLIP INVESTMENT OPPORTUNITY
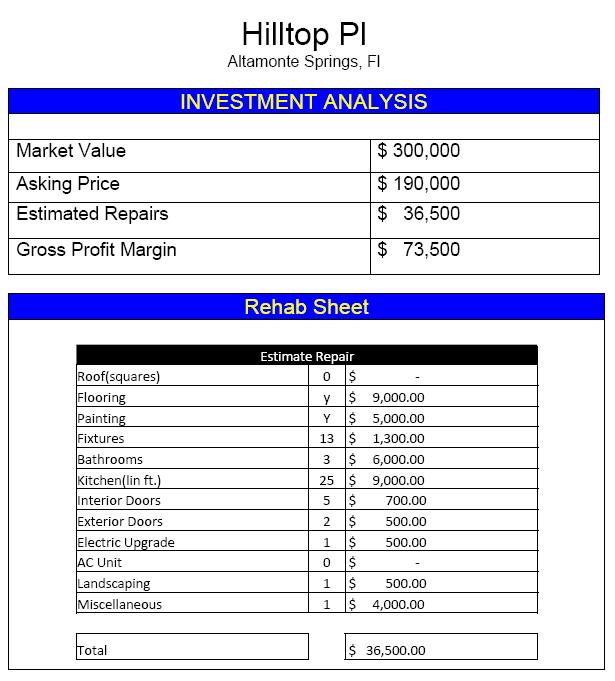
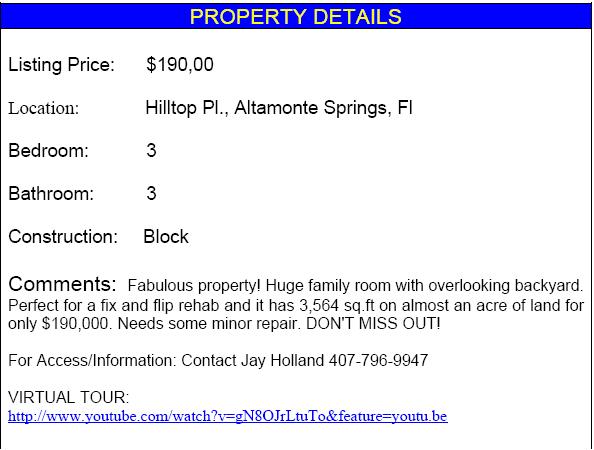
FOR SALE IN ALTA MONTE SPRINGS
Showing posts with label real estate investment in Florida. Show all posts
Monday, January 28, 2013
Alta Monte Springs Huge House Investment
Monday, October 24, 2011
Second Mortgage What Is It Exactly
The real term for this is called a home equity loan. This is a common loan type that homeowners can use for whatever they want.
A home equity loan requires that you use your house for collateral just like a normal home loan. There are
different types of home equity loan out there and you can always use the money for whatever you want.
College, bills, and home repairs are some common uses. You will need outstanding credit to be approved for this kind of loan though.
A closed end type home equity loan gives you a big chunk of money immediately and you can’t get another loan until this one is fully paid.
The amount you can get depends on factors such as how much your home is worth, your income, credit score, and similar things. A closed end loan usually comes as a fixed rate type and allows you up to 15 years to pay it off.
An open ended home equity loan is a little different. This loan will let you borrow money whenever you have a need for it.
The loan lender will set up a line of credit that is pretty much based on all the same factors as the closed end loan. These usually have an adjustable rate and you can make payment for 10, 15, or even 30 years.
So why are these called second mortgages Because you are adding yet another loan payment that uses your house as collateral and adding another monthly payment. Though tempting, it can cause you a lot of problems in the future.
Rard Haugabrooks -Chief Review Appraiser
ROI Homes is helping investors throughout Central Florida realize their potential and acts as a guiding light through the rehabilitation process and rejuvenating the community one home at a time!
Thursday, September 22, 2011
Discover Proven Debt Relief....Christian Debt Consolidation
Do you know for sure Christian debt consolidation is legitimate and not just a scam? The truth is there are some of the so called "Christian Debt Consolidation" companies that are rip offs. However, there are many very legitimate, non-profit, faith based organizations to help Christians.
There are some specific things you should check for to determine if it is a legitimate Christian service or not. The information you gather here will help you make the right decision.
One of the first steps you should take in choosing a true Christian organization to help you is to check with your local Pastor. There is a good chance he or she will be able to refer you with no problem. However, if your local Pastor can't help you, one of the larger Churches in your area will be able to assist you.
Many of today’s Christian congregations have a specific ministry set up for the purpose of debt counseling. Not only will they council you about debt consolidation, but they will provide you with a full spectrum of biblical based financial counseling.
These counseling sessions will cover:
1. Money Management
2. Budgeting
3. Debt Elimination
4. Debt Relief
5. Christian Debt Consolidation
6. Debt Reorganization
7. Possible Bankruptcy
Each of these programs will be presented and taught to you so as you won’t have to comprise your Christian doctrine.
When you first began talking with any organization you always verify they are a legitimate non-profit service. If you are talking with them on the phone or in person you should ask them for proof of their non-profit status. You will find the legitimate ones will have no problem with providing documentation.
However, if they are on the questionable side of being a legitimate Christian service they will do what they can to avoid producing the appropriate documents.
A very good indication of a true Christian counseling service, there will be no high pressure tactics to get you to sign up for the service. If you should detect or sense the councilor you are talking to is using “closing techniques”, it would be best to terminate the conversation.
High pressure closing tactics are put into play for one reason and one reason only. It is to get you to sign on the dotted line right that instant. In other words they have their own interest at heart and not yours.
A legitimate Christian debt councilor will not use “sales closing” strategies. Their goal will be to get a commitment from you to commit to changing your financial life. These folks know for a fact, unless you are fully prepared to make a lifestyle change, in your spending, money management and budgeting, nothing will change.
The other not so “true Christian debt service” will not care if you make any changes or not. Primarily they want you to come crawling back to them again in a few years to put more money on their bottom line. In fact they know if they play their cards right you will be a lifetime customer.
As you have learned there are legitimate and not so legitimate Christian debt consolidation organizations. It is important for you to be able to make the right choice, so you will indeed have a solution for your debt problems.
ROI Homes is helping investors throughout Central Florida realize their potential and acts as a guiding light through the rehabilitation process and rejuvenating the community one home at a time!
We scour through hundresd of homes for sale, analyze properties to find the ones which after renovation have the best return on investment and pick them up and offer them to investors at wholesale price. We have several homes in the 50-60,000 range that after 15-20,000 worth of renovations will be able to be resold at reatail for $110-120,000. I can show you these properties.Tuesday, September 20, 2011
Tips About Unsecured Debt Consolidations
www.myroihome.wordpress.com
Are you ready to throw in the towel on ever getting out of debt? Don’t do it. You may have a chance to reduce your debt with unsecured debt consolidation loans. These loans are somewhat more difficult to obtain, but it is well worth the effort. You will find tips on how to use unsecured consolidation loans to put you back in charge of your debt. Instead of the debt controlling you, you will control your debt.
First, it is important for you to understand the difference between unsecured loans and secured loans.
Let’s suppose you are a student just starting out your freshman year of college. Shortly after being accepted by your school of choice, you started receiving pre-approved credit cards. You accepted the offer and within 10 days or so you received your card. The first thing you did is go out and buy text books for your classes; to the tune of several hundred dollars.
Being short on cash you put it on your new credit card. You just made your first unsecured debt. If you forfeit on the loan for some reason, the credit card company can sue you, but they can’t take your school books from you. You did not have to use the books for collateral to get the cash to pay the book store.
Now let’s say you need to take a student loan to pay tuition, lab fees, additional books, housing, food and etc. Because of the amount you need, the bank or lending institution has said they will loan you the money. However, to get it, you or someone, is going to have to put up collateral to secure the loan. Just in case you forfeit on the loan, this gives the bank the right to foreclose on whatever property was put up to secure the loan.
It’s time to move forward and the years have passed and all your student loans, family debts and credit card bills are burying you. You need a way out, but you don’t own any real property. Other than your car and it has a lien against it.
Your first step is to go to your personal bank and apply for an unsecured debt consolidation loans. If you have a good record with your bank, no hot checks or defaulted on any loans with them, you may well qualify for an unsecured consolidation loan.
Your personal banker will work with you to determine which of your loans should be consolidated in the new loan and which ones will not be. One of the reasons for doing this is most credit card interest rates will be much higher than a bank loan. However, depending on the type of student loans you have, you may have a lower interest rate, than what the consolidation loan will have.
There is also a good chance your bank may have a credit counseling service or be able to refer you a reputable non-profit credit counselor. This service could prove to be invaluable to you so as you don’t get yourself in over your head later on.
Normally you will find many unsecured debt consolidation loans will range from six months to five years. Whereas most secured consolidation loans will have a longer time for repayment from 10 years and up. Obviously the shorter the time frame for repayment the quicker you will get your debt reduced.
As you have seen there are two types of consolidation loans you may qualify for. Both have the same goal and this is to reduce your debt burden.
Depending on what your personal situation is and your ability to repay unsecured debt consolidation loans you may find the relief you are seeking.
ROI Homes is helping investors throughout Central Florida realize their potential and acts as a guiding light through the rehabilitation process and rejuvenating the community one home at a time!
We scour through hundresd of homes for sale, analyze properties to find the ones which after renovation have the best return on investment and pick them up and offer them to investors at wholesale price. We have several homes in the 50-60,000 range that after 15-20,000 worth of renovations will be able to be resold at reatail for $110-120,000. I can show you these properties.
Subscribe to:
Posts (Atom)
