Showing posts with label real estate in Florida. Show all posts

Friday, October 21, 2011

Signs Of Good Mortgage Brokers

www.ihd.postlets.com
www.myroihome.wordpress.com


A good mortgage broker is something every potential homeowner or experienced real estate investor needs to have on their side.

There is no shortage of brokers out there and they come in all shapes and sizes with various personalities.

What people don’t realize is that if you have a very  helpful and friendly broker, it can really make a difference in your entire attitude about getting a loan.

When you have a good mortgage broker, you will usually have a pretty stress-free loan process and they will be able to explain it all to you simply and easily.

So how do you know if you have a good broker There are some very simple things that will tell you right away if your broker is good or not.

One of the best ways to judge a mortgage broker is just with common sense. Does your broker like to talk and have an excited attitude

That can definitely improve the experience for you but there are other factors to consider. Punctuality is very important and someone missing dates can be infuriating.

If your broker says they will call at 6 pm and they miss it every time, it might be a problem. You really want someone very punctual.

The broker should be able to list off mortgages and programs by heart as well. It’s not a good sign if they are flipping through a book every few minutes to look up terms and arrangements.

A good way to tell if your mortgage broker is good is to make sure they are willing to answer any question imaginable without getting frustrated.

Ask them something a couple times in one sitting just to see what they do. If it’s obvious they are annoyed and don’t ask why you repeated it, they might not be paying attention and just reciting some spiel they use on everyone.

Thursday, September 22, 2011

Discover Proven Debt Relief....Christian Debt Consolidation

Do you know for sure Christian debt consolidation is legitimate and not just a scam? The truth is there are some of the so called "Christian Debt Consolidation" companies that are rip offs. However, there are many very legitimate, non-profit, faith based organizations to help Christians.

There are some specific things you should check for to determine if it is a legitimate Christian service or not. The information you gather here will help you make the right decision.

One of the first steps you should take in choosing a true Christian organization to help you is to check with your local Pastor. There is a good chance he or she will be able to refer you with no problem. However, if your local Pastor can't help you, one of the larger Churches in your area will be able to assist you.

Many of today’s Christian congregations have a specific ministry set up for the purpose of debt counseling. Not only will they council you about debt consolidation, but they will provide you with a full spectrum of biblical based financial counseling.

These counseling sessions will cover:
1.    Money Management
2.    Budgeting
3.    Debt Elimination
4.    Debt Relief
5.    Christian Debt Consolidation
6.    Debt Reorganization
7.    Possible Bankruptcy

Each of these programs will be presented and taught to you so as you won’t have to comprise your Christian doctrine.

When you first began talking with any organization you always verify they are a legitimate non-profit service. If you are talking with them on the phone or in person you should ask them for proof of their non-profit status. You will find the legitimate ones will have no problem with providing documentation.

However, if they are on the questionable side of being a legitimate Christian service they will do what they can to avoid producing the appropriate documents.

A very good indication of a true Christian counseling service, there will be no high pressure tactics to get you to sign up for the service. If you should detect or sense the councilor you are talking to is using “closing techniques”, it would be best to terminate the conversation.

High pressure closing tactics are put into play for one reason and one reason only. It is to get you to sign on the dotted line right that instant. In other words they have their own interest at heart and not yours.
A legitimate Christian debt councilor will not use “sales closing” strategies. Their goal will be to get a commitment from you to commit to changing your financial life. These folks know for a fact, unless you are fully prepared to make a lifestyle change, in your spending, money management and budgeting, nothing will change.

The other not so “true Christian debt service” will not care if you make any changes or not. Primarily they want you to come crawling back to them again in a few years to put more money on their bottom line. In fact they know if they play their cards right you will be a lifetime customer.

As you have learned there are legitimate and not so legitimate Christian debt consolidation organizations. It is important for you to be able to make the right choice, so you will indeed have a solution for your debt problems.   


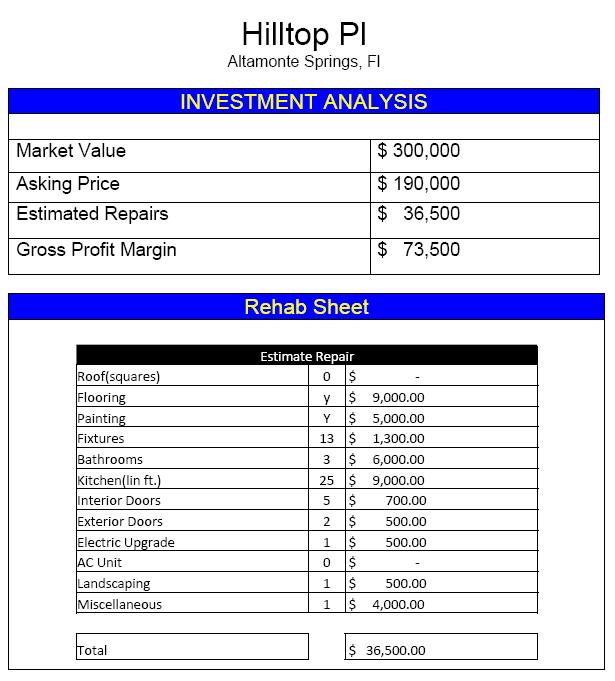
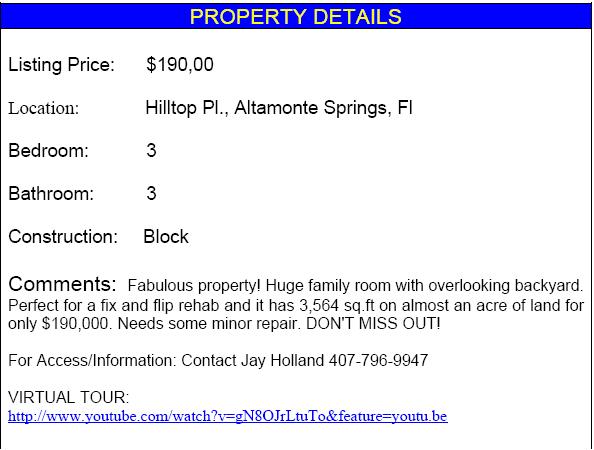
ROI Homes is helping investors throughout Central Florida realize their potential and acts as a guiding light through the rehabilitation process and rejuvenating the community one home at a time!

We scour through hundresd of homes for sale, analyze properties to find the ones which after renovation have the best return on investment and pick them up and offer them to investors at wholesale price. We have several homes in the 50-60,000 range that after 15-20,000 worth of renovations will be able to be resold at reatail for $110-120,000. I can show you these properties.
Wednesday, September 21, 2011

Tips About American Credit Counseling

   www.ihd.postlets.com
www.myroihome.wordpress.com
 
You have read all the hype and listened to all the commercials about American credit counseling, haven't you? Almost every one of them has promised to get you out of debt, eliminate your bad credit report and do it all legally. Right?

In addition you have heard many of them proclaim to be non profit. You begin thinking "Oh boy! There going to do it for free". Guess what? Don't you believe it! If you do you're in for a rude awakening.

Many of these companies that make these claims are just barely within the law. They aren't quite cheating you and lying to you, but they are pretty darn close. As you get into the fine print of their claims and contracts, you begin to discover the real truth.

First of all these companies can no more expunge your bad credit than the man in the moon. Much less do it legally. The only legal way to get bad credit off your credit report is to pay what you owe.

But the fact is every late payment, defaulted loan and any other piece of bad credit goes on your report, including the record of your debt consolidation stays on your record. Currently all this information will be available to lenders, insurance companies, employers and others, for a period of seven years. What good are they then? You might ask.

The American credit counseling company can take the burden off your shoulders of negotiating with the companies you owe money to. They will set up a mutually agreed on plan with your lenders on consolidating all your payments; into one lump sum. There is also a chance they can get the interest rates lowered on your loans.

In addition, they are experts at stopping the collection calls and may even be able to reduce your late and over balance fees. This is all well and good. But guess what, you can do it yourself, of course these companies don't tell you that. Why, because they want to get paid for their service.

Next let's talk about the nonprofit claims. It is true many of these companies can file for and be granted nonprofit status by the United States federal government. But everybody that works for those companies has to make a living. So you will be charged a fee for using their service.
www.ihd.postlets.com
www.myroihome.wordpress.com

You will be surprised to learn many of these companies don’t disclose these hidden fees to you. After you have contracted for their services you will send them your lump sum payment. However, prior to disbursing your money you were paying before; they take their hidden fee off the top.

What this means for you is the amount going to your lenders is less than what you thought you were paying. The possible end result being that it still takes you years to pay off the debt. Plus the fees could end up being more money than the lowered interest rates benefited you.

It is extremely important for you to get every bit of information you can from the American credit counseling companies. They can help you, but they can also make your financial situation even more desperate than it already is. 

ROI Homes is helping investors throughout Central Florida realize their potential and acts as a guiding light through the rehabilitation process and rejuvenating the community one home at a time!

We scour through hundresd of homes for sale, analyze properties to find the ones which after renovation have the best return on investment and pick them up and offer them to investors at wholesale price. We have several homes in the 50-60,000 range that after 15-20,000 worth of renovations will be able to be resold at reatail for $110-120,000. I can show you these properties.

Monday, September 19, 2011

Secret About Debt Negotiating

www.myroihome.wordpress.com
www.ihd.postlets.com
 
First let's get a brief review of Part 1 and then move into Part 2 of "Secrets About Debt Negotiating And Protecting Your Rights".

If you are in financial trouble in the United States or other countries you have the right to debt negotiating. In other words, you can bargain with your lenders to try and get better terms to pay off your debt.

You are going to need to be prepared when you start this process. The people you are going to be talking to are professionals and they know precisely what to say and how they can say it. Therefore it is imperative for you to know your rights also.

There are basically three ways to learn what your rights are.

1.    Visit the FTC (Federal Trade Commission) website http://www.ftc.gov/bcp/edu/pubs/consumer/credit/cre18.shtm
2.    Visit your states official web site and find your rights in your particular state. Normally you will find this in the State Attorney General part of the site.
3.    Seek advice from a qualified debt attorney. And hire him to do the negotiations for you.

The third choice can get expensive very quickly. Here are some additional tips you can rely on if you want to do your own debt negotiating.

•    Keep records
•    You should keep a journal or at least a note pad of every time you have contact with a lender.  Do it when they call you and you call them. You should note the following in your journal:

o    Date and Time
o    Name of collection agency
o    First and Last name of who you talked to
o    Notes on what was said

If by chance you and your lender reach a debt repayment plan, it is imperative to get it in writing. Do not make a payment until you have the agreement in writing. However, remember when you get it in writing it is a double edged sword. It can work for you and it can work against you.

There are two ways for you to do that. You can request the debt collector to mail you a letter confirming the agreement exactly the way it was discussed on the phone. Make sure that it is on their company letter head and signed by an officer of the company or someone else with legal authority to sign the letter.

Actually the best way to get it in writing is for you to draft a letter to the lender, laying out the terms as you understand them. Be sure and send this letter by certified mail, return receipt requested. This gives you the proof you need to show you have acted in good faith.

One thing you may not really understand is that the collection company and their representative cannot rush you into making an agreement and payment. No matter what they say or how hard they “brow beat” you don't make any payment until you have it in writing and signed by an official.

If you will notice in the above paragraph we mention a debt collector using "brow beating" tactics to rush you. Listen and listen good folks! You are protected under the  Federal Consumer Protection Act and more than likely your own state has a very similar protection for you from those types of tactics.

The following is just a few of the things a debt collector cannot do:

•    No harassment
•    Abuse you (verbally or in writing)
•    No cussing or indecent language
•    No phone calls on a consistent basis
•    Cannot contact your employer (when you notify the collection company your employer is prejudiced against these calls)
•    Plus many more (which are beyond the scope of this article)

Are you aware that if the collection agency infringes on your rights you have the legal right to report them to state and federal authorities. You can even sue them and collect damages in some cases.

You have the right to do debt negotiating in good faith. You should know what you can do and not do. Be prepared!

Oh yeah! Don't forget about the tape recorder I told you about in Part 1 of "Secrets About Debt Negotiating And Protecting Your Rights".

Friday, September 16, 2011

How You Can Profit With Your Business Credit Report

www.myroihome.wordpress.com
http://ihd.postlets.com

As a small business person one of the most important assets you have is your Business Credit Report? Along with your own personal character and a good credit report you can just about name your own ticket in your local community. Furthermore, it can help you expand you business to the far reaches of the world. This article will give you some ideas of how important your credit report is to your profit.

As an astute business person you know you will have to contact new customers. In a lot of cases when you do the new customers want to know how reliable you are. Not only will they be looking for personal references but they want to know you are sound financially.

They may ask you to furnish credit references and other information about you and your company. Many times these new customers will use your business and personal credit report, to verify your financial stability and personal character. By chance, if you happen to have reports of outstanding debt, which has been unpaid or public judgments for failure to finish projects, your chances of landing this new customer are slim to none.

Not only can the above circumstances affect your ability to grow your business, it may prevent you from obtaining proper business insurance. In many cases you may have to carry a large umbrella policy for liability, before you can bid on certain jobs or actually perform the job function. In today’s modern society you and your company can be sued for anything and everything.

Without a proper credit rating, as reflected by your business or personal credit report, you may be refused insurance all together. If you are not insured you may be considered a higher risk and end up having to pay an outrages premium. Whereas with a good business credit report the insurance companies may look very favorably upon giving you a large discount off the premium.

One of the most lucrative forms of business for a small business is government contracts. Once again your personal and business report will be verified. This becomes especially important if your company and you are required to have a security clearance in order just to bid on the project. A reflection of bad credit on your credit report can stop a security clearance or other government contracts dead in the water.

However, with your outstanding credit and personal character, because you are a small business owner you can have a leg up on the larger companies. The reason for this is the Federal government; of the United States has special preference programs for the small business owners. This means you may be able to add another stream of income to your bottom line. Once again you can see how your credit report can help make you profit.

Here is a little tip that can help you keep your business credit report looking good and help your cash flow at the same time. Most companies, when they extend credit, will give favorable repayment terms to your small business, provided your credit worthy. If the term is Invoice Net 10 days, most companies will not report you as long as you get the invoice paid before 30 days are up.

If you are in a cash flow crunch, have your bookkeeper set up to pay the invoice before the 30th of the month. Make sure the bookkeeper allows enough time for the mail. This tip should only be used discreetly and infrequently. Otherwise you will get a reputation of using your vendors to finance your business operations for 30 days.

There is a drawback to this kind of credit repayment. Many of your vendors now will start calculating a late fee and interest payments as soon as the 10 days is up. So instead of enhancing your cash flow it can further deplete it.

You as an ethical business person have the responsibility of keeping your debts paid and paid on time. When you do this you have seen how your business credit report can be a profit center for you.

Thursday, September 15, 2011

TIPS ABOUT AMERICAN CREDIT COUNSELING

www.myroihome.wordpress.com
www.ihd.postlets.com


You have read all the hype and listened to all the commercials about American credit counseling, haven't you? Almost every one of them has promised to get you out of debt, eliminate your bad credit report and do it all legally. Right?

In addition you have heard many of them proclaim to be non profit. You begin thinking "Oh boy! There going to do it for free". Guess what? Don't you believe it! If you do you're in for a rude awakening.

Many of these companies that make these claims are just barely within the law. They aren't quite cheating you and lying to you, but they are pretty darn close. As you get into the fine print of their claims and contracts, you begin to discover the real truth.

First of all these companies can no more expunge your bad credit than the man in the moon. Much less do it legally. The only legal way to get bad credit off your credit report is to pay what you owe.

But the fact is every late payment, defaulted loan and any other piece of bad credit goes on your report, including the record of your debt consolidation stays on your record. Currently all this information will be available to lenders, insurance companies, employers and others, for a period of seven years. What good are they then? You might ask.

The American credit counseling company can take the burden off your shoulders of negotiating with the companies you owe money to. They will set up a mutually agreed on plan with your lenders on consolidating all your payments; into one lump sum. There is also a chance they can get the interest rates lowered on your loans.

In addition, they are experts at stopping the collection calls and may even be able to reduce your late and over balance fees. This is all well and good. But guess what, you can do it yourself, of course these companies don't tell you that. Why, because they want to get paid for their service.

Next let's talk about the nonprofit claims. It is true many of these companies can file for and be granted nonprofit status by the United States federal government. But everybody that works for those companies has to make a living. So you will be charged a fee for using their service.

You will be surprised to learn many of these companies don’t disclose these hidden fees to you. After you have contracted for their services you will send them your lump sum payment. However, prior to disbursing your money you were paying before; they take their hidden fee off the top.

What this means for you is the amount going to your lenders is less than what you thought you were paying. The possible end result being that it still takes you years to pay off the debt. Plus the fees could end up being more money than the lowered interest rates benefited you.

It is extremely important for you to get every bit of information you can from the American credit counseling companies. They can help you, but they can also make your financial situation even more desperate than it already is.

Wednesday, September 14, 2011

Tips On How To Keep Your Credit Score High


www.ihd.postlets.com
www.myroihome.wordpress.com
Were you aware that your credit report score is what will either make you or break you when you apply for a loan or credit card? And this is just a plain fact. The fact is the majority of companies that give credit use it to determine if you get your loan or not.

These tips contained in this article will give you a good idea of how your credit score can work for you or against you.

When you are first starting out in the world of credit it can be a Catch 22 for you. If you have no credit history your credit score will be low. Therefore when you first apply for a loan the chances are you may be turned down.

However, there is a way to build up your credit score. Once you have gainful employment you can go to a consumer store and purchase a low dollar ticket item of several hundred dollars. Your monthly terms will be low but take the time to make your payments on time over 6 to 8 months.

By doing so this will factor into your credit report score when you go back to apply for a larger dollar amount on credit. Once you show you have been on the job and made your payments on time your overall credit report score will move up.

What can cause your credit score to go down?

1. Debt To Income Ratio
This means you have obligated yourself to pay back a high amount of your salary to monthly obligations. Let's say your monthly income is $2000 and your monthly pay out is $1700 in obligated debt. Your debt percentage is 70% of your income. Not a good idea!

2. Slow Payments
Once your payment becomes 30 days late it is reported to the credit bureau. Even one late payment will lower your score.

Where this really becomes a threat to your credit score is when you don't catch up the payment. The only way you can do that is to pay the late one and the very next one on time.

If you don't do this the 30 day late payment will increase in number and each time it shows late it lowers your score.

3. Repossessions and Foreclosures
If you have a car, furniture or any other item foreclosed on this will go on your credit report for 7 years. It will continue to keep your score lower because of them.

This list could go on and on, but let's look how you can keep your score up.

It is important for you make your payments on time. A continuous record of on time payments will continue to drive your score up. The longer you have a good record the higher your credit report score will be.

The higher your score, the more likely the chances of you being able to buy a good home, a high priced car and other toys on credit.  However, just because you have the ability to do so does not mean it's a good idea to rush out there and do so.

To be straight forward about it there are many things which factor into your credit score being high or low. However, when you apply common sense to your credit worthiness you have an excellent chance of keep your credit report score high.

Tuesday, September 13, 2011

Secrets About Debt Negotiating and Protecting Your Rights

 www.ihd.postlets.com
www.myroihome.wordpress.com

You’re sitting at dinner with your family and the telephone rings. It's a bill collector and they are demanding you pay them right now. Today! Tonight! Guess What? You don't have to do that. You have the right to what is called debt negotiating.

Very simply put this means when you are in financial trouble and can't pay your bills, you have the right to negotiate with your lenders, regardless of who they are. In addition, if the bill has been turned over to a collection agency, you can bargain with them also. However, this may not be quite as easy as it sounds.

Don't let this information scare you, use it to your advantage when you are talking with debt collectors. You are going to be dealing with someone who knows what they can say and how they can say it, when collecting a debt. This means it's critical for you to know your rights before starting the discussion.

One of the fastest ways for you to learn your rights is to go on-line to the Federal Trade Commission site. This official U.S. Government on-line brochure can be printed out so you will have it at your disposal day or night. You will find this brochure on-line at http://www.ftc.gov/bcp/edu/pubs/consumer/credit/cre18.shtm.

In addition, many of the individual states have their own laws about debt collection. A quick check on-line with your states official site will fill you in on your rights and the bill collector’s rights. In addition, there are other ways to protect yourself.

Did you know that in 35 states in America, plus Washington, D.C., you can secretly record phone conversations? In the 15 other states, you can record a telephone conversation provided you advise the other person you are doing so.

You should check with your states Attorney General, on-line, to make sure where your state stands on this issue. Any time you are involved in debt negotiating with a lender or collector, always try to have a tape recorder hooked up.

It's a tool which works like magic during a negotiation. You would be surprised how calm and helpful lenders and debt collectors become when they are being recorded. However, you need to bear in mind that a recording can work both ways. Be sure to make only statements and commitments you can keep.

You do not have to let them bully you into making financial commitments you can't keep. Even though they insist you do it their way, make no mistake, you have the right to discuss the debt in full. Rationally and calmly! Determine what you can pay and then offer less than the amount. This way it gives you additional bargaining power, as the collector is going to try and bump up that amount. Never go over the amount you can pay.

Remember, one of the reasons you are in this 'debtor’s hell' is you overextended yourself. Trying to pay back more than you can will only dig the hole that much deeper.

This is only the first installment in a two part series on “Secrets About Debt Negotiating And Protecting Your Rights”. Be sure and read Part 2 of this article.

Monday, September 12, 2011

Discover The Truth About Credit Report Repair

                                                                   www.ihd.postlets.com
www.myroihome.wordpress.com

Did you just try to get a loan for car repairs and get turned down? That is a horrible feeling and it even makes you feel you have let your family and yourself down. Right? Don’t get desperate and run out to hire a company to do a credit report repair. You may find yourself in worse shape than before you started. This article may well give you 2nd thoughts about using one of these companies.

Chances are you have seen the ads for “Legally Repair Your Credit Report”, “Wipe Your Credit Report Clean In 7 Days”, “Buy A New House With A Clean Credit Repot” etc. You have been sitting in your favorite recliner watching the TV and suddenly somebody starts telling you can have a clean credit report in as little 30 days.

Hold on to your wallet if you are thinking about calling them. No matter what promise these companies make, bad credit transactions are going to stay on your personal credit report. They cannot wave a magic wand and make your bad debts vanish; like magic.

What you are hearing and reading is a first class con job, being played on desperate people. Many of these companies have been put out of business by the FTC (Federal Trade Commission) and local states Attorney General. The sad part is there are those that remain in business and continue to rake in $1000.00s of dollars per month from unsuspecting people.

Even some of the companies still in existence are a fly by night operation. You pay them a fee from as low as several hundred dollars to a high of perhaps a thousand or more. They collect your money and the next time you call them the phone has been disconnected.

However, there are some that actually offer a legitimate service. But you are going to be paying them to do something you can do yourself. All they are going to do is take the list of your debts, fill in a form letter to your lenders and ask them to prove the debt. Hey! You can do your credit report repair yourself.

O.K. are you now asking how you clean up your own credit transcript. You are most likely not going to believe this but the process is simple, but it can take some time.

Several years ago, the Federal Government of the United States, made it mandatory that the consumer had the right to get a copy of his credit report once a year. So the first step you have to take is write or call the “Big 3”, TransUnion, Experian and Equifax, and request a copy. By law they have to send you a current copy of your credit narrative.

If you should find false information reported by a creditor, your next step is write the company about their false information. By law, in 30 days, they must either prove the debt or have it removed if false. However, if you find the reported debts on your report are accurate, this is where the rubber hits the pavement. Because they will remain on your report for 7 years or until you clean them up.

When you hear the outrageous claims made by these companies, the old adage applies; “If it sounds to good to be true it probably is.”

In Part 2 of “Discover The Truth About Credit Report Repair” it will give you more information on how you can legally clean up your own credit transcript.